I’m Eddie Biesenbach. If you’re considering a unit or an established home in Greerton, I help you understand the borrowing alongside the property costs. I work with first-home buyers, people moving to a smaller home and investors who want the numbers and documents checked.
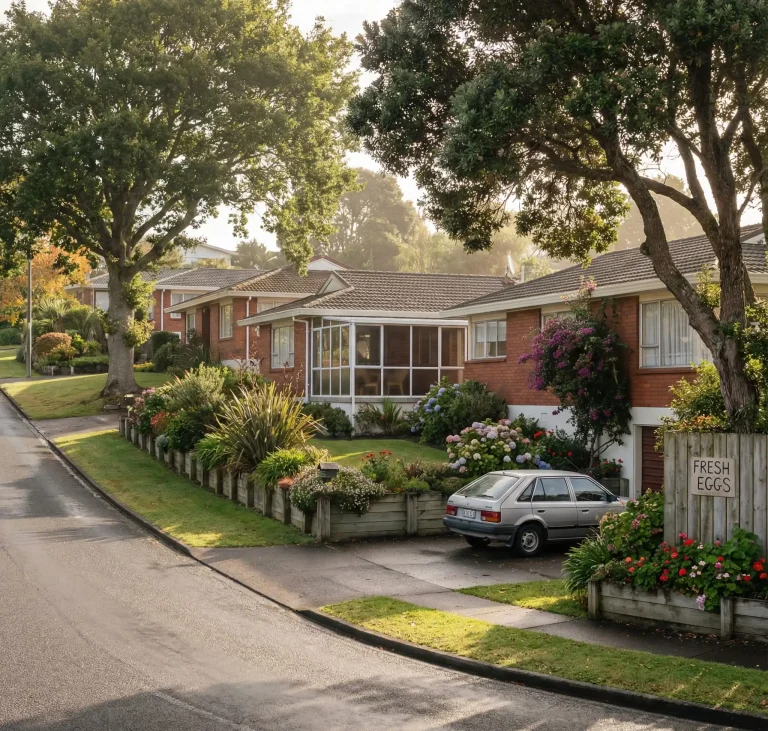
Greerton Village’s shops and services, and Te Ao Mārama–Greerton Library on Greerton Road, give buyers recognisable places to consider when thinking about daily life. I ask what being close to those amenities is worth to you, alongside parking, access and the home’s upkeep.
A compact floor plan does not tell us how the property is owned or what you will pay to maintain it. When you send me a listing, I want to know whether it is freehold, cross lease or unit title, and whether any shared costs need to be included in the lending discussion. Your lawyer confirms the legal position.
These are useful checks for a first home or a smaller next home. A property described as a “unit” does not necessarily have a body corporate.
I ask you to have your lawyer check the record of title, access and any relevant restrictions. If it is cross lease, ask whether the plans match the existing buildings and alterations. I then establish whether the lender needs further information.
For a unit title, I ask about body corporate levies and the available disclosure documents. For other ownership arrangements, I ask what insurance and shared maintenance costs you have identified. I include the known costs in the budget rather than treating them as incidental.
I want to understand any inspection findings or planned work that could affect your cash reserves. For a unit title, have your lawyer review the maintenance plan, financial position and relevant meeting records. I can then discuss the borrowing implications of the costs identified.
I compare the proposed mortgage payment with rates, insurance, levies where applicable and your regular spending. I ask what money would remain for repairs or an unexpected bill. A manageable purchase price is only one part of a sustainable home-loan plan.
Imagine a first-home buyer choosing between two Greerton units at a similar asking price. One is cross lease. The other is unit title, with levies and planned shared work described in the disclosure documents. Both look manageable in a quick mortgage calculator.
I would compare the full household costs and the cash needed after settlement, using verified figures and the buyer’s income. Their lawyer would explain the different rights and obligations. I would then check the chosen property with the lender, rather than assume that approval for a price range covers either home. This is a hypothetical comparison, not a real buyer’s story or a promised result.
If your Greerton choice is a standalone house, I ask about its condition, any additions and what you want to improve after moving in. I help identify information the lender may request, while your building professional checks the physical property and your lawyer reviews the records.
If the home fronts a busy road or has shared access, I encourage you to visit at different times and consider how it would work for you. I do not assume that a road location automatically changes a lender’s decision. Where a valuation is required, I check how the lender wants it ordered before you incur that cost.
If you’re buying to live in it, my first-home buyer service covers preparation, the application and the steps toward settlement. I can help you start with a realistic budget even before you choose a property.
If you’re considering a rental, my investment-property lending service looks at borrowing and cash-flow commitments. I ask you to obtain an appropriate rental assessment and advice on landlord obligations. I do not assume that a Greerton address guarantees tenants, a particular rent or a return.
I can assess the proposal, but I need the actual property details as well as your financial position. Title, size, condition, insurance and any shared costs may be relevant. I check the lender’s requirements for that property instead of promising acceptance of every unit.
No. “Unit” can describe the building without identifying its legal ownership. I ask you to have your lawyer confirm the title. If it is a unit title, I include the body corporate information in the finance preparation; a cross lease has a different legal structure.
I include the actual levies with the mortgage and other regular costs. I also ask whether the documents identify planned work or additional funding needs. The current levy is not a guarantee of future costs, so I want you to understand what has and has not been budgeted.
I would assess affordability from the specific home and your circumstances. That includes the deposit, repayments, debts and ongoing ownership costs. I cannot promise that every Greerton property is affordable or use a suburb-wide price claim as a substitute for your budget.
I can help with an early lending assessment and an application for conditional pre-approval where appropriate. When you find a unit, I still need to check the property and any outstanding lender conditions. Speak to your lawyer about the purchase agreement and its deadlines.
I help make the lending steps understandable, particularly when you are buying for the first time. You can work directly with me from the initial budget discussion through the mortgage application. Read about my lending background or client reviews to get a feel for my approach.
For your next step, contact me. I also cover Tauranga’s other suburbs, with a broader overview on my Tauranga mortgage advice page.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.