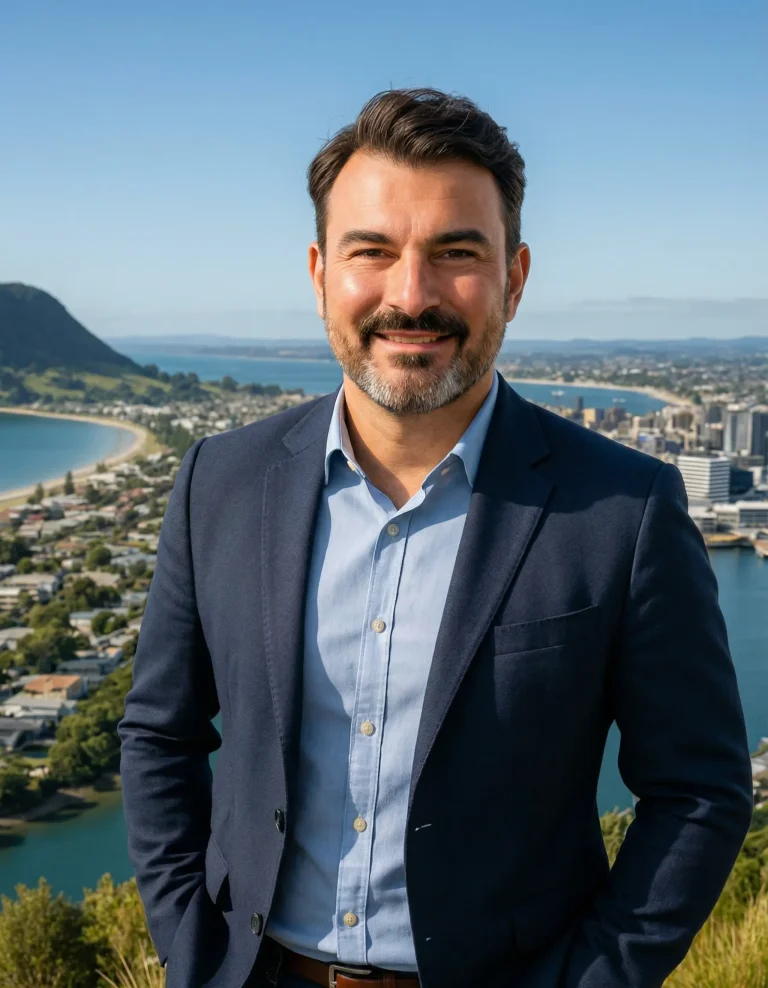
I’m Eddie Biesenbach, the adviser behind Best Mortgages. I’m based in Tauranga and bring more than 20 years of lending experience to help you understand your home loan options. Whether you’re buying, refinancing or investing, I can help you prepare an application and compare suitable lenders, loan features and costs.
You work directly with me, with mobile and online appointments and after-hours meetings by arrangement. Start with a free, no-obligation conversation about what you’re planning.
A common issue I see with Tauranga first-home buyers is uncertainty about the whole buying process, not just the mortgage. People can find a house they love before they know what finance might be available, when to organise a KiwiSaver withdrawal or what other costs to allow for.
My usual starting point is to understand your finances before you commit to a property. I review your income, deposit and commitments with you before an application goes to a lender. If you’re ready, I help you prepare. If you need more time, I can work with you on a plan.
I’ve worked with clients for more than a year while they built their deposit or improved the way they managed their accounts. An initial conversation is still useful if you’re hoping to buy later rather than now. It can help you understand what needs attention and what information to prepare.
The property matters too. An apartment in Mount Maunganui, an established home in Greerton and a new build in The Lakes can raise different questions. I help you work through the lending side and identify what the lender needs. For property, legal, tax or insurance advice, I’ll point you towards the appropriate professional.
You can explore the Tauranga areas I serve or read on for the lending situations I help with.
The interest rate matters, but so do repayment flexibility, fees and how the loan fits your plans. I explain suitable fixed, floating or split options and any relevant features. The aim is to make the trade-offs clear, including what happens if you want to make extra payments or change the loan later.
I help present your income, deposit and commitments clearly, explain the supporting documents needed and work through lender questions with you. An application should reflect your actual circumstances, including any changes you expect. The lender assesses the application and makes the lending decision.
If you’re buying your first home, we can talk through your deposit, possible KiwiSaver withdrawal and the steps towards an application. Lower-deposit lending depends on lender criteria and your circumstances. We can also discuss what to prepare if you’re not ready to apply yet.
A construction loan and an investment property loan can involve different documents and planning. I can help you consider the purchase or build, how it would be funded and how repayments fit with your existing commitments. The relevant service pages explain these situations in more detail.
If your fixed rate is ending or you’re considering changing lenders, I can help you review refixing and refinancing options. We look beyond an advertised rate to fees, any costs of leaving the current loan, repayment flexibility and the structure you need. Moving lenders is not automatically the best choice.
If other repayments are putting pressure on your budget, we can discuss whether debt consolidation through a home loan is appropriate. A lower regular payment does not necessarily mean a lower total cost, particularly if repayment is spread over a longer term. The costs and risks need careful consideration.
Being self-employed or earning variable income can mean the application needs more explanation. The useful starting point is a clear picture of your income, commitments and the documents available. I can help identify what information a lender may need and whether suitable options are available.
If one bank has already declined an application, tell me why if you know. We can review the position rather than assume a different lender will approve it. Sometimes another option may be suitable; sometimes the sensible next step is to improve the deposit, documentation or overall position before applying again.
There is no need to choose a loan product before we talk. Start with your plans and the questions you have.
Helping you get the loan is only part of my role. I particularly enjoy helping first-home buyers understand how the lending steps fit with the rest of the purchase. I can liaise about the mortgage-related steps with your agent, builder or lawyer where needed, while they provide their own specialist advice.
You should know what is happening, why information is needed and which decisions are still yours to make. These are the usual lending steps; the detail depends on your situation and the lender.
Start with a free, no-obligation conversation about what you want to do, your timing and any questions. Bring what you know about your income, deposit, existing loans and the property, if you have one in mind.
I review your circumstances and compare suitable options from lenders I work with. We discuss the features, costs and structure, and the reasons for a recommendation. You can ask questions before deciding how to proceed.
With your agreement, I help prepare and submit the application, respond to lender questions and explain any approval conditions. Pre-approval is conditional, and lending approval and timing depend on the lender and your circumstances.
I help you understand the next lending steps as settlement approaches. Your lawyer handles the legal work. You can also come back when a fixed rate is ending or you need to review the loan because your plans have changed.
I compare suitable options from the banks and non-bank lenders I work with. That does not mean every loan in the market is available through me. I’ll explain the options considered, why a recommendation fits your circumstances and the relevant costs and features.
For most standard home loans, there is usually no adviser fee because the lender pays a commission. If an adviser fee applies, I’ll explain it upfront. My Public Disclosure Statement sets out further information about fees, commissions and the advice service.
I can review the reasons, your documents and whether another lender may be suitable. A decline from one lender does not always close every option, but another approval is not guaranteed. We can also discuss practical preparation if applying again is not the right next step.
I’m based in Tauranga and offer mobile appointments around Tauranga and the Bay of Plenty, including Papamoa, Mount Maunganui and Pyes Pa. We can agree a suitable time and place. Online meetings are also available, including for clients elsewhere in New Zealand.
Timing varies by lender, application complexity and the information required. Complete documents can help avoid unnecessary delays, but there is no guaranteed turnaround. Tell me about any purchase deadline early so we can discuss the time available and what needs to happen.
Buying, reviewing your loan or just working out where to start? Tell me what you’re planning and I can help you work out the next useful step. The initial conversation is free and there’s no obligation to proceed.
My support is not just for the purchase. You can come back when you need to refix, consider a top-up or review your lending as your plans change.
Learn more about my background and Best Mortgages, read client reviews or explore my home loan services. For direct help, contact me or call 021 449 177.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.