I’m Eddie Biesenbach. Buying a home in The Lakes starts with a straightforward question: does the house, its paperwork and the ongoing cost fit your plans? I help you assess the mortgage for the actual property, including any changes you hope to make after moving in.
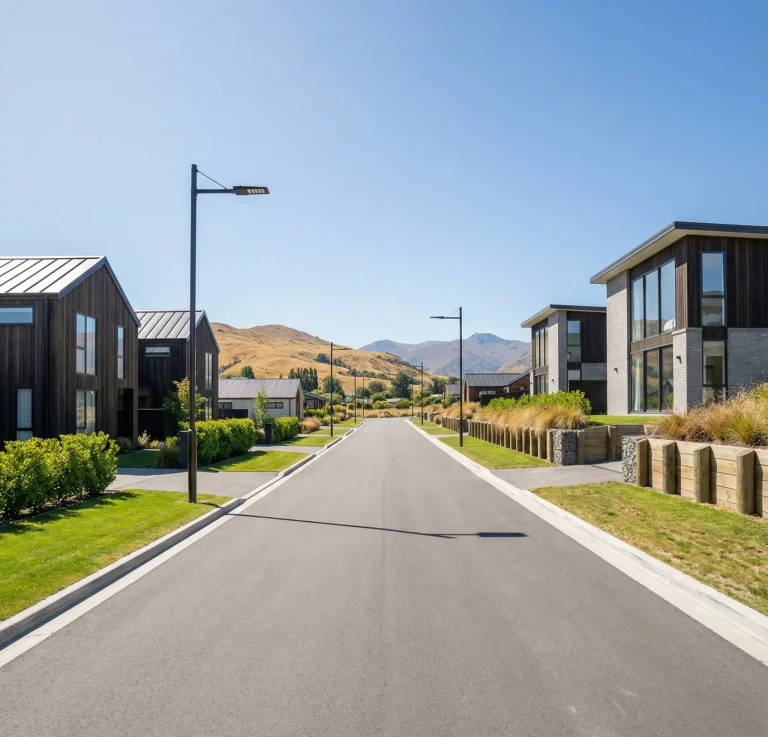
The Lakes is part of Pyes Pa West, with its own network of reserves and walkways. Caslani Reserve on Caslani Lane and Orangapani Reserve on Lakes Boulevard are useful reference points when choosing a street and checking your daily routine. The wider Pyes Pa area includes different established-home and lifestyle-property choices.
I treat a home in this subdivision as an individual property. A recently built appearance tells me little about its title restrictions, later alterations or your ability to afford it. I ask what has been built, what documents are available and whether you want to change anything. That gives the finance discussion a practical starting point.
What the title allows. Ask your lawyer to review any covenants, easements and other interests on the specific title. If adding a room, changing fencing or using space for a business is important, raise it before purchase. I do not assume the same restrictions apply to every property in The Lakes.
What the building records show. Ask for the relevant consents, completion records and information about later work. A code compliance certificate relates to the work covered by its building consent. It is useful evidence, but I still encourage a property inspection and questions about maintenance. I can check which documents the lender needs without certifying the building myself.
What ownership will actually cost. I ask for the current rates assessment and an insurance quote for the address. Council’s 2026/27 rates information includes a Pyes Pa West urban infrastructure targeted rate within a defined area. Check the property’s own assessment rather than applying a neighbour’s bill. Include planned upkeep and alterations in your budget too.
If this is your first purchase, I can help through my first-home buyer service. I work through the deposit and repayment plan before you depend on a borrowing figure. If you already own in The Lakes and need more space, my renovation lending service can help you assess a proposed extension or other work.
For a loan review without building work, I can discuss refixing and refinancing. I look at the purpose of the review, remaining loan term and any costs of changing the loan, alongside the interest-rate options.
Imagine a buyer considering a completed home in The Lakes near a reserve. The layout works now, but they hope to add a room for working from home. They are deciding whether to spend their remaining cash on a larger deposit or keep it for that project.
I would compare the purchase-only budget with a properly costed improvement plan. Before relying on the extension, their lawyer would check title restrictions and a designer or council adviser would clarify what is feasible. I would then check the lending requirements and revised repayments. This is a hypothetical example, not a real client case or a promise that an extension or loan will be approved.
I help you see which finance questions are resolved and which still need an answer, rather than assuming that a completed-looking home has a completed file.
Tell me the price range, deposit and timing, and whether the property is already complete. I ask about your income and commitments and the amount you want left for life after settlement.
List the alterations that matter to you. I keep an optional future wish separate from essential work, so you can decide whether the home still suits you if that project cannot proceed.
I clarify the lender’s property and financial information requirements. Your lawyer reviews the title and agreement; your building adviser checks the house. Tell me if either finds something that changes the plan.
I explain the conditions attached to an offer and help coordinate the mortgage steps with your lawyer. A pre-approval still needs the property and any outstanding conditions to be addressed.
I would not assume that. The property’s history, the purchase arrangement and the lender’s current definition matter. I check the transaction before discussing a suitable product or deposit requirement; the suburb name does not settle it.
I would ask your lawyer to check the individual title and relevant documents. Restrictions can affect intended alterations or use, so I want you to understand those before building an important future project into the finance plan.
Ask your lawyer and council to establish what work the record relates to and what remains unresolved. I can clarify the lender’s requirements once the position is understood. I cannot certify compliance or promise that finance will be available without the missing information.
I can assess a proposal using your finances, the existing loan and the documented project. Further borrowing is subject to assessment. I help you compare the proposed repayments and term, while the relevant professionals advise on design, covenants, consent and cost.
No. I also ask about the actual rates, insurance, maintenance and other household commitments. A calculator can help explore repayment amounts, but it does not review the title, assess the property or confirm that a lender will approve your application.
You work directly with me, Eddie Biesenbach, from the first discussion through the mortgage process. I’m Tauranga-based with more than 20 years of lending experience overall. You can read how I work and my background before we discuss the home, the paperwork and the budget you want to keep.
Compare locations in the Tauranga suburb guide or see my broader Tauranga mortgage advice.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.