A home near Main Beach, an apartment around Pilot Bay and a property you plan to rent out can need different finance conversations. I’m Eddie Biesenbach, and I help you check the details before relying on a borrowing figure.
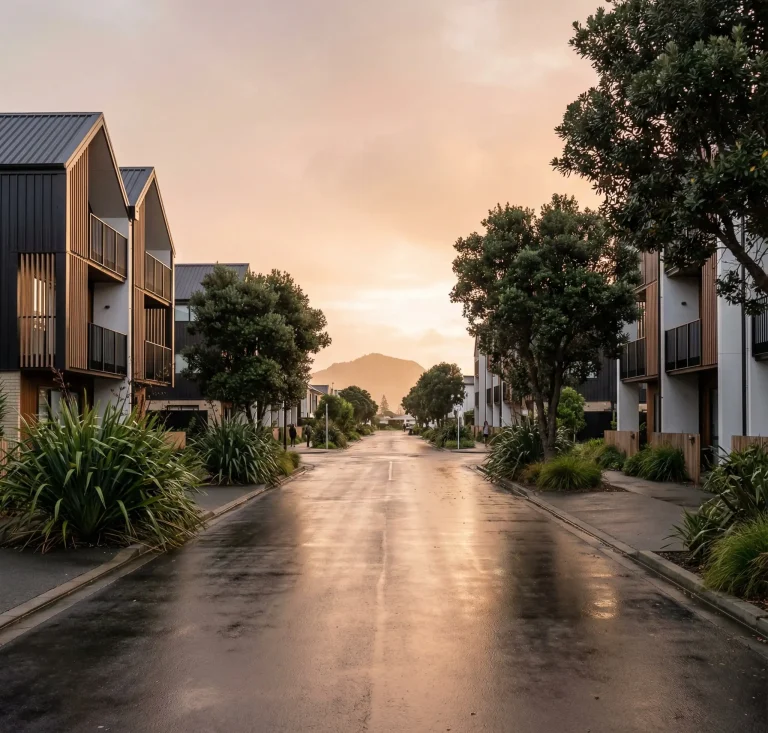
Mauao, Main Beach and Pilot Bay give Mount Maunganui a distinctive coastal setting. When you find a property here, I want to know whether it will be your everyday home, a place for holidays or an investment. That intention belongs in the finance discussion from the start, alongside your income, deposit and existing commitments.
I also ask what you are buying. A standalone house, cross-lease home and unit-title apartment bring different ownership questions. If you are choosing between a beachside apartment and a house further from the waterfront, I can compare the borrowing and ongoing costs while your lawyer checks the title and your building adviser assesses the property. There is no single “Mount mortgage” that suits every address.
This example is hypothetical, not a past client result. A buyer finds an apartment near Pilot Bay and initially plans to live there. They also wonder whether they could let it to holiday visitors when away.
I would ask them to settle the intended use before the application is assessed, and to have their lawyer check any relevant restrictions and council requirements. I would then confirm the lender’s approach and the evidence it needs, without assuming occasional letting income can support the loan. The buyer would also need insurance advice for that use. This avoids building a borrowing plan around income or permissions that have not been established.
I help translate the relevant findings into questions for the lender. I do not assess building safety or interpret an insurance policy: those answers need the appropriate building professional, lawyer or insurer. Raising an issue early gives you time to understand it before a finance deadline.
For a first home at the Mount, I help work through the deposit and application evidence through my first-home buyer service. If you plan to rent the property out, I discuss investment lending using the costs and income evidence relevant to your intended use. Rental demand or holiday income should not be assumed from the location.
Already own here? My mortgage review and refinancing service compares your current arrangement with alternatives. I look at the remaining loan term, repayment flexibility and switching costs as well as the interest rate. A change of lender still requires an assessment of both you and the property.
You do not need every document ready for an initial chat. A property listing and a clear explanation of your plans are a practical starting point.
I review how you will use the property, your income, debts and deposit, and what repayments would leave room for normal living costs.
I check the title and building information needed by the lender, including body corporate documents where relevant. I flag missing items for you and your advisers.
I explain any valuation, insurance or other requirements and the difference between a general pre-approval and approval for your chosen property.
I discuss the structure and repayment options in light of your plans, including how a future move or change of use could affect the arrangement.
No conclusion should be drawn from that alone. I check the property details and the lender’s requirements, while your insurer assesses the address and cover. Hazard maps and the LIM are starting points for property-specific questions, rather than a blanket verdict on coastal homes.
Possibly, but I need to check your finances and the exact apartment. Title, use, building details and the lender’s current criteria all matter. I will not promise a particular deposit percentage or approval simply because the apartment is at the Mount.
Tell me before the application is submitted. I can check the lender’s approach to the proposed use and income. You should also confirm permitted use and any ownership restrictions with your lawyer and council, and discuss suitable cover with an insurer.
Do not assume it will. I can help establish what the lender still needs for the particular property. Get your lawyer’s advice and complete the finance and property checks before bidding or making any other unconditional commitment.
Yes. Bring the offer, its conditions and the property details. I can help you understand the proposed structure and what remains outstanding. A second conversation does not guarantee a lower rate or different lending decision.
I’m Tauranga-based, with more than 20 years of finance and lending experience and a mobile, flexible approach. You can get to know me and read genuine client reviews before making contact. Send me the Mount listing and tell me what you want the property to do for you.
Explore other Tauranga locations or read how I provide mortgage advice across Tauranga.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.