I’m Eddie Biesenbach. For a Brookfield house or unit, I help you bring the purchase budget and the property paperwork together. If a cross-lease home has been altered, I want the important questions raised before you depend on the finance.
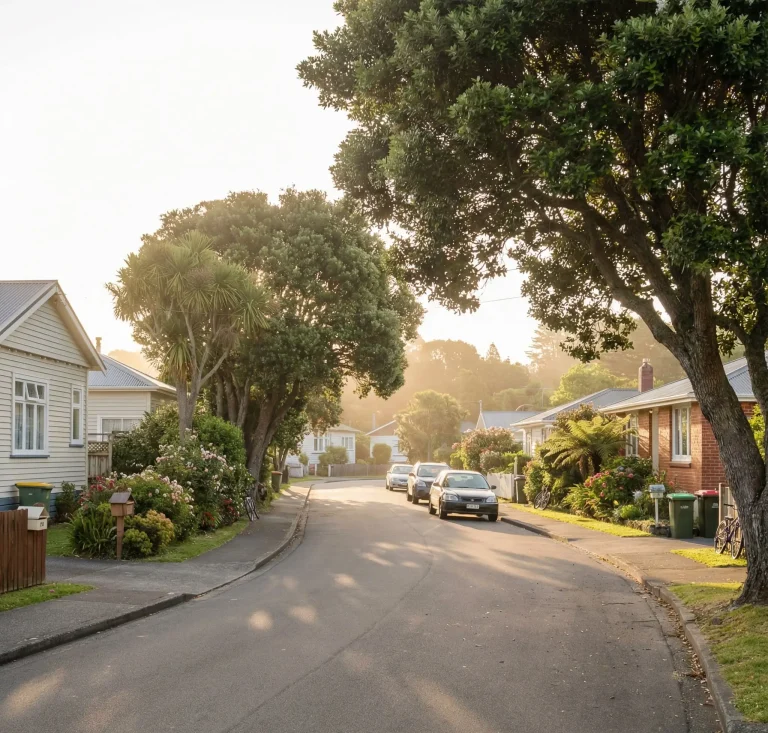
Brookfield’s centre sits where Ōtūmoetai, Waihi and Bellevue Roads meet. If being close to those shops and connections is part of your decision, I also ask how the particular home works: its access, parking, layout and upkeep. A convenient address does not replace a careful look at what you are buying.
An older unit with a new kitchen may still have an extension, enclosed space or shared access that needs checking. For a cross-lease property, I ask you to have your lawyer compare the title documents and any flats plan with the home as it stands. Council consent records and the ownership documents answer different questions.
I do not treat a cross lease as an automatic obstacle or a promise of easy approval. My job is to explain the lender’s requirements and prepare the finance using the information available. Your lawyer, surveyor and building professional establish what any discrepancy means and how it could be resolved.
A smaller property can still have a detailed file. I help keep the finance questions organised without taking over the legal or building advice.
I review your income, deposit and existing commitments. We include ownership costs and a reserve for the property checks and work you may need.
Send me the listing and the documents available. I identify lender requirements while your lawyer and building adviser review the title, plans and physical condition.
If the records and property differ, I clarify the finance implications with the lender. You get specialist advice about the issue and your purchase conditions.
I explain the lender’s remaining conditions and discuss the loan structure. Check with your lawyer before making an unconditional commitment.
If something needs clarification, I ask what evidence and time the lender requires. Your lawyer should advise on the contract and any appropriate conditions. I would not build a purchase timetable on the assumption that a title update or other remedial work will be quick or inexpensive.
For a first purchase, I help separate the deposit from legal, inspection, valuation and moving costs, then consider the money left for repairs. My first-home buyer service covers the wider application and approval process.
If you are buying a Brookfield rental, I review investment lending against the expected income and costs, using supporting evidence. The property’s ownership, maintenance needs and landlord obligations still matter. I do not assume a rental return from being near the shopping centre.
For an existing home, my refinancing and mortgage review service can compare your current loan with alternatives. Tell me if you have extended or changed the property since the original loan: a different lender may need current information, and past acceptance does not settle every future application.
Imagine a first-home buyer considering a Brookfield cross-lease unit with an enclosed porch used as an extra room. The listing photos look appealing, but the buyer is unsure whether the current footprint matches the flats plan. This is a hypothetical example, not a past client result.
I would ask the buyer’s lawyer to establish the title position and a building professional to assess the physical work. I would check what the lender needs, including any valuation requirements, while the buyer considers the cost and timing of the outstanding checks. I would not describe the room as approved living space or promise finance simply because the purchase price fits the initial budget.
I can assess the proposal with a lender, but acceptance depends on the property and your circumstances. I ask for the title information and any relevant alterations or inspection findings before relying on an approval.
Have your lawyer advise on the discrepancy and whether a surveyor or updated documents are needed. I can ask the lender what it requires. Do not assume building consent alone resolves a separate title issue, or that you can leave it until after settlement.
No. Council records and an inspection serve different purposes. I encourage you to have the paperwork reviewed and the actual home assessed by an appropriate building professional. I then use relevant findings to clarify the lending requirements.
I check the lender’s valuation requirements for the specific application. It may need a registered valuation or another acceptable assessment. Before ordering a valuation, ask how it must be commissioned so you do not pay for a report the lender cannot use.
Yes. I can help work through your deposit, income, purchase costs and application. We also check the particular unit’s title and condition. I assess what fits your budget rather than describing all Brookfield units as affordable.
You work directly with me. I have more than 20 years of finance and lending experience, including Barclays International on the Isle of Man and three New Zealand banks. Read about Eddie or what clients say, then send me the Brookfield listing, your budget and any date you need to work towards. We can identify the next useful check.
Compare nearby locations through the Tauranga area guide. For the broader service, see my mortgage advice across Tauranga.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.