I’m Eddie Biesenbach. I help Otumoetai buyers and homeowners work through their home-loan options, from buying an established home to downsizing or funding improvements. I look at the property, your repayments and the timing of your move together.
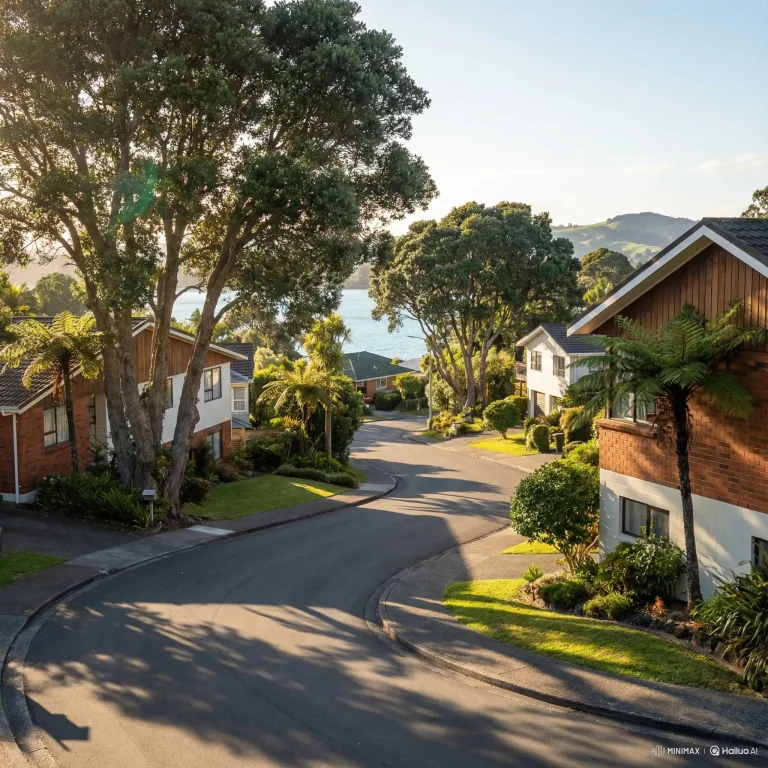
If you’re looking around Ōtūmoetai, the harbour edge and Kulim Park may be part of what draws you here. A single-level home, less garden to manage or room for family can matter just as much as the asking price. I start by asking what you want this move to change.
For an established or renovated property, I want the lending plan to reflect its actual condition and records. If you’re selling as well, I also look at what money will be available on each settlement date. A lower purchase price does not, by itself, resolve the funding gap between two homes.
Imagine a couple planning to reduce their working hours and move to a single-level Otumoetai home. They expect to lower their mortgage, but the purchase would settle before their existing home sells. They also want savings available for moving and future maintenance.
I would assess repayments against their planned lower income and calculate the borrowing during and after the move. I would also allow for a more cautious sale price and longer overlap before comparing funding choices. Their lawyer would advise on dates and conditions. This is a hypothetical planning example, not a story about a client or an approval outcome.
The borrowing after the move. I work through your current loan, expected sale proceeds, purchase costs and the cash you want to keep aside. I ask about planned changes to working hours or income so the proposed repayment term fits the next stage of your life.
The house behind the listing. For an older home with an added room, enclosed deck or converted garage, I ask what council records and inspection reports are available. Your lawyer and building professional assess the documents and work; I clarify what the lender needs and whether an issue remains unresolved.
The order of the transactions. I compare selling first, aligning settlement dates or seeking short-term bridging finance if appropriate. Bridging involves costs and the risk of carrying two properties or receiving less for the sale than expected. I would check its suitability and lender approval before you rely on it.
If staying would meet your needs, I can compare refixing, refinancing or restructuring your existing mortgage before you decide to move. I look at fees, any fixed-rate break costs and the remaining term, as well as the repayment.
For a layout change or extension, my construction and renovation lending service helps you plan the proposed borrowing and payment stages. I assess income and commitments alongside equity; an estimate of your home’s value is not an approval to spend.
I keep the next step clear, especially when a sale, purchase and existing fixed loan all need to be considered.
I ask about income, regular spending, debts and the money you want left after moving. I distinguish the repayment you are comfortable with from the maximum a lender might consider.
I review your existing lending, likely settlement dates and whether sale proceeds are already confirmed. I help identify the finance questions for your lawyer before you commit to the purchase agreement.
I help gather the financial evidence and the information the lender requests for the chosen home. I explain any conditions that remain, rather than treating conditional pre-approval as approval of every property.
I coordinate mortgage-related steps with your lender and lawyer, discuss the loan structure and confirm what is outstanding. After the move, you can come back to me when your fixed term, income or plans change.
I can assess the move with your existing loan in place. I need to understand what will be repaid from the sale, the new purchase cost and your ongoing income. A smaller home can still need temporary funding if the purchase settles before the sale.
I would compare the options for your circumstances. Buying first can create extra borrowing and sale-price uncertainty. Bridging is subject to lender criteria and is not suitable or available for everyone. Your lawyer should advise on any sale condition and settlement commitments.
I ask for the available property records and refer technical or consent questions to your lawyer and building professional. The lender may need further information about particular work. I cannot confirm compliance from a listing, and I would not assume every alteration required the same consent.
I can assess that as part of the purchase plan or as a later application. I consider the cost and scope of the work, your income, commitments and available equity. If improvements are essential, I prefer to address their funding before you rely on a later top-up.
Start with your plans, an outline of your income and existing mortgage, and a property link if you have one. Tell me whether your current home is listed or under contract. I can then explain which documents would be useful and the questions to resolve first.
I bring more than 20 years of overall lending experience to my work at Best Mortgages. You deal with me directly, and I explain the options and outstanding conditions in plain language. Read about my background or what clients say about working with me.
I also help across Tauranga’s suburbs. For an overview of my service, see my Tauranga mortgage advice page, or contact me about your plans.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.