I’m Eddie Biesenbach. I help Welcome Bay buyers and homeowners work through their home lending, including the extra questions a sloping section or retaining wall can raise. I focus on your budget, the available property evidence and what needs resolving before you commit.
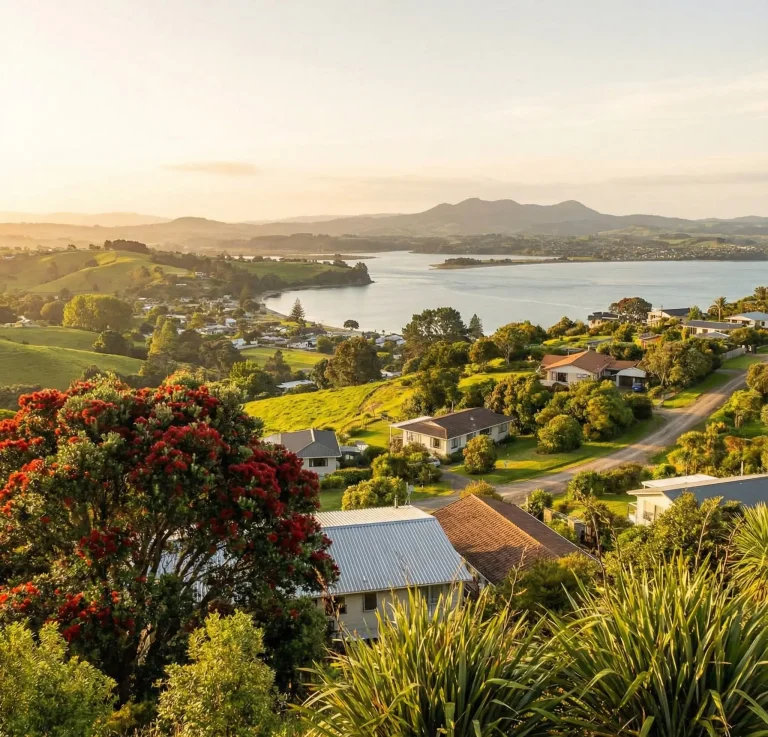
Welcome Bay’s Waitaha Reserve and neighbouring community centre are useful reference points when considering how a home would fit your day-to-day life. On a property with changes in ground level, I would also want you to look closely at access, drainage and the costs of maintaining the site.
My role is to help with the finance. I cannot assess the stability of a slope or certify retaining work. I help identify questions that need a qualified professional, then clarify what the lender requires for the particular property. A general statement about Welcome Bay cannot establish the risk of an individual address.
Imagine buyers interested in a Welcome Bay house with a terraced garden and an older retaining wall. Their initial budget is workable, but the building inspection recommends specialist advice about the wall and drainage. The finance deadline is approaching.
I would clarify the lender’s information requirements and ask the buyers to arrange the appropriate professional assessment. Once the scope and likely cost are clearer, I would revisit the budget and application. Their lawyer would advise on the contract, deadlines and any request for more time. I would not describe a conditional approval as permission to ignore the unresolved issue. This is a hypothetical planning example, not a client case or a prediction of lender approval.
I help you separate what is known, what needs investigation and what the lender still needs before making its decision.
I review income, deposit or equity, debts and household expenses. I include the ongoing costs you have identified for the home and ask what reserve you want for maintenance or unexpected work.
Send me the listing and any reports already available. I help identify missing information for the lending application and clarify which questions belong with your lawyer, insurer, building professional or engineer.
If an inspection or specialist report changes the picture, I revisit the cost and funding assumptions with you. A revised proposal may need lender review. I explain the implications rather than assume the original loan amount still works.
I help coordinate the mortgage-related requirements with the lender and lawyer. I explain outstanding conditions and discuss the final loan structure, so you know what remains to be resolved before relying on the finance.
Current council information. I encourage you to obtain property records and have the LIM and relevant hazard information reviewed. Tauranga’s city-wide landslide mapping is a screening tool, not a site-specific geotechnical assessment. If there is a concern, an appropriately qualified professional needs to assess the actual ground conditions.
Retaining walls, drainage and past work. I ask what plans, reports and completion records are available. Whether particular work required consent is a question for the council and your advisers; the height of a wall alone does not settle every issue. I check any lending requirements without interpreting the engineering myself.
Insurance and future spending. I ask you to check insurance availability and terms for the property early. If repairs, drainage changes or retaining work are proposed, I want reliable cost advice and a funding plan. I would not treat uncertain future borrowing as money already available to fix an identified problem.
For a first purchase, my first-home buyer service helps with the budget, financial evidence and wider mortgage process. A property can suit your lifestyle while still needing more investigation before you commit.
If you already own in Welcome Bay and want to alter the house or undertake significant site work, I can discuss renovation and construction lending. I look at the documented scope, costs and proposed repayments, and check the lender’s requirements. I leave design, safety and consent decisions with the relevant professionals.
I cannot decide that from the contour or suburb alone. I look at the available property information and clarify the lender’s requirements. Where an inspection identifies a concern, a qualified specialist may need to investigate it before the lending proposal can be fully assessed.
Yes. I start with your income, deposit or equity, current commitments and the repayments you want to manage. If you already own a home, I also look at sale timing and the existing loan. You can talk to me before you have chosen a property.
I would ask you to discuss the current map and LIM with your advisers and provide relevant findings for the lending assessment. The council’s broad mapping does not predict that a landslide will occur at a particular house. Nor does it replace a site-specific assessment where one is needed.
I can assess a funding proposal once the intended work and likely cost are clear. Your income, commitments, equity and the lender’s assessment all matter. Have the appropriate professional advise on scope and consents; I help plan the lending rather than specify the construction solution.
Tell me and your lawyer promptly. I can clarify what the lender still needs and whether a revised application is required. Your lawyer advises on contractual options and any extension request. I cannot promise an extension, a report turnaround or approval by the original deadline.
I bring more than 20 years of overall lending experience and work with a range of bank and non-bank lenders. You deal with me directly. Read about my background, then tell me which Welcome Bay property or project you are considering.
You can contact me, compare the Tauranga areas I serve or explore my broader Tauranga mortgage service.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.