If you’re moving to Bethlehem, the important number is what the next home will cost you after the move is complete. I’m Eddie Biesenbach. I help you work through the equity, sale timing and repayments before you commit to a purchase.
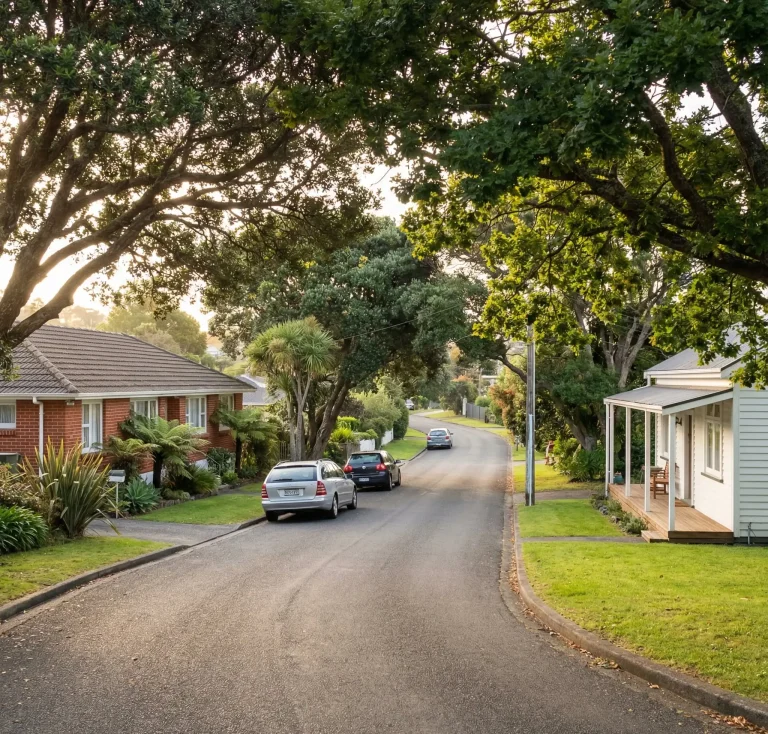
Bethlehem Town Centre, established subdivisions such as Bethlehem Heights and Mayfield, and the walkways around Gordon Carmichael Reserve give you several local settings to consider. Your preferred street, house size and daily routine belong in the discussion alongside the price. I help turn those plans into a borrowing budget that leaves room for living in the home.
For a family moving from another property, I start with the existing mortgage, likely sale proceeds, costs of selling and buying, and the cash you want to retain. If your household income is changing, tell me early. A larger home can bring different rates, insurance and maintenance costs, and the bank’s maximum lending figure may be more than you want to repay.
For a first purchase in Bethlehem, there is no sale to coordinate, but the deposit and ongoing budget still need the same care. I can help with first-home lending preparation before you narrow down a property.
Gordon Carmichael Reserve includes wetlands and links Bethlehem with Brookfield and Bellevue. The wider Bethlehem area also sits near the Wairoa River. Those local features are useful context, but I would not label every nearby home with the same risk. Have your lawyer review the address-specific LIM and title, confirm insurance and seek specialist advice where needed.
If staying put is an option, I can look at borrowing for improvements through renovation lending and compare that budget with the cost of moving. Consent, valuation and building requirements depend on the work; extra borrowing still needs approval.
When a fixed term is ending, my refinancing and refixing advice considers the remaining loan term and total costs as well as repayments. If you are thinking of retaining your current home as a rental, I can assess the investment lending implications. I would revisit the borrowing plan rather than simply substitute rent for the sale proceeds.
A clear timeline helps me identify the decisions that need to happen first. Bring the current loan details and tell me whether a sale, purchase or fixed-rate expiry is driving the date.
I review income, commitments, current borrowing and deposit or equity, with a realistic allowance for transaction costs and a cash reserve.
I discuss selling first, buying first or keeping the existing home, and check which options the lender can assess for your circumstances.
I help organise the finance evidence for the chosen property. Your lawyer checks the agreement, title and any conditions protecting the move.
I explain the proposed loan structure and the repayment position after settlement, including any temporary borrowing that still has to be cleared.
This is a hypothetical planning example, not an account of a client result. A household finds a home in Bethlehem that better suits their family, but their existing property has not sold. They expect to use the sale proceeds towards the purchase and also want to replace the kitchen.
I would separate the temporary funding need from the eventual mortgage, test a lower sale-proceeds assumption and include the costs of carrying both properties if relevant. I would also keep the kitchen budget visible rather than assume it can be borrowed later. The lender would decide whether the proposed arrangement is acceptable, and the lawyer would advise on purchase and sale conditions. The family can then judge whether to proceed, change the sequence or adjust the budget.
Potentially. I check the current loan, property value, proposed borrowing and your ability to meet repayments. Equity is one part of the assessment; it does not create automatic approval or mean all of it can be used as a deposit.
That depends on your finances, timing and tolerance for uncertainty. Selling first can give you clearer proceeds and avoid overlapping home loans. Buying first may need additional funding. I can compare the lending implications while your lawyer advises on the agreements.
I can check whether it is a suitable option and whether a lender will consider it. I look at the repayment plan, expected sale and ability to cover the overlap. Availability and terms are individual, so do not commit on the assumption that bridging will be approved.
The particular property matters more than an age label. A building inspection, LIM, title review and insurance enquiry can identify issues to investigate. I also ask about improvements you intend to make so those costs are considered alongside the mortgage.
It might, but a lower monthly payment alone does not prove a saving. I compare interest, fees, any break costs or cashback repayment, and the remaining term. Extending the loan can reduce regular payments while increasing total interest over time.
You work directly with me, with more than 20 years of finance and lending experience behind the conversation. Learn about Eddie and Best Mortgages and read client reviews. Contact me with your current loan balance, the approximate purchase budget and the dates you are working towards. I can help identify a practical next step.
Considering another suburb too? Browse the Tauranga location guide or see my wider Tauranga mortgage advice service.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.