I’m Eddie Biesenbach. I help Matua buyers and homeowners plan their home lending, whether you’re buying near the harbour, improving an established home or reviewing the mortgage you already have. I bring the property questions and the borrowing decisions into the same conversation.
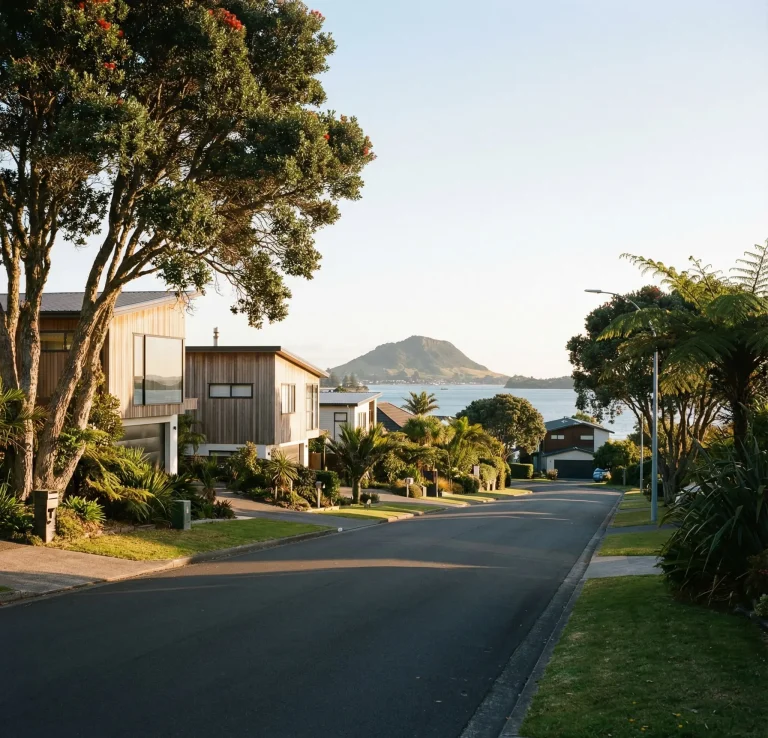
Fergusson Park on Tilby Drive and the walkways around Papahenga–Matua Saltmarsh are recognisable parts of Matua. If access to those places is a reason you’re looking here, I also want you to consider the particular house, its land and the costs of owning it.
An established family home, a renovated property and a smaller home for downsizing can raise different questions. I do not infer the condition, insurability or lending suitability of a property from its address or a harbour view. I help you work out what needs checking before the finance decision.
Address-specific hazard and insurance information. I encourage you to review the current council information with your advisers and ask an insurer about the actual property early. Harbour inundation mapping includes different scenarios; a map is not an insurance decision. I then clarify the lender’s insurance requirements.
The history of the building. If the home has been extended or substantially changed, I ask about the available council records and inspection findings. Your lawyer and building professional assess those records. I focus on what the lender needs to consider the security and any proposed work.
Costs that continue after settlement. I include rates, insurance and a maintenance allowance in the budget discussion. If you plan to change the layout, roof or outdoor areas, I ask you to get costed advice rather than assume the purchase loan leaves enough room for every improvement.
I start with the work you actually want done, the quotes available and when payments would fall due. A smaller improvement and a substantial extension can call for different funding arrangements. I check whether a top-up, staged lending or another structure is suitable, including any valuation or completion evidence the lender requires.
I also compare the cost of staying with your lender against changing lenders where relevant. My refinancing service covers that comparison; my construction and renovation lending service explains the project-funding side. Extra borrowing remains subject to assessment, even when you have equity.
If you’re buying your first home here, I can also help with first-home lending preparation.
I use these questions to keep the funding plan connected to the property and your everyday budget.
I separate the purchase or essential work from improvements that could wait. I ask about savings you want to retain, existing debt and household costs, then discuss a realistic borrowing plan.
I identify the financial and property documents needed for the application. Where the issue is technical, I ask you to obtain advice from the appropriate building, legal or insurance professional and help communicate relevant findings to the lender.
I compare the contract or renovation payment schedule with the lender’s proposed release of funds. I ask about contingencies and temporary accommodation if relevant, rather than assuming every invoice can be paid from the first drawdown.
I discuss the term and structure for the completed borrowing. I want you to understand the ongoing payment and total-cost trade-offs, especially if a proposed restructure would extend how long you carry the debt.
Imagine a Matua homeowner planning a kitchen replacement and an extension. The kitchen has a firm quote, but the extension still needs design work and a reliable budget. The owner is also close to the end of a fixed mortgage term.
I would compare funding the defined work first with waiting until the full project is ready for assessment. I would check the existing loan, any costs of changing it, and whether the lender needs further property or build evidence. I would leave room for the possibility that the later work costs more or is not approved for funding. This is an illustrative planning situation, not a completed client project.
I would check the actual property and available evidence. The suburb name alone cannot answer that. I encourage early insurance enquiries and appropriate review of council hazard information, then confirm any property-specific questions raised by the lender.
I look at the condition and documentation rather than treating age alone as a problem. Particular building issues, incomplete work or missing information may need investigation. I help clarify the lender’s requirements; a qualified building professional assesses the building itself.
I can assess whether additional borrowing is suitable. Equity is only one part of that assessment: income, expenses, current commitments, the work and the proposed repayments also matter. I would confirm the funding arrangement before you commit to spending that depends on a loan.
Not necessarily. I may be able to compare a top-up or restructure with your current lender against switching. I include relevant fees and any break costs, and consider the repayment term. The choice should fit the project and your circumstances, rather than a headline rate alone.
Yes. I can help assess the budget and prepare an application, then work through the chosen property and any finance conditions. My first-home buyer service explains the wider preparation, including the documents I may ask you to gather.
You can speak directly with me about the home, the work you’re considering and what you want the mortgage to achieve. My banking and mortgage-lending background helps me ask practical questions early. You can read more about me before getting in touch.
I can help you compare the next step for your home. Contact me, explore other Tauranga suburbs or read how I work as a Tauranga mortgage adviser.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.