In Papamoa, I start by asking whether you’re buying an existing home, a completed new build or a home that still needs to be built. I’m Eddie Biesenbach, and I help you understand what that choice means for the finance and timing.
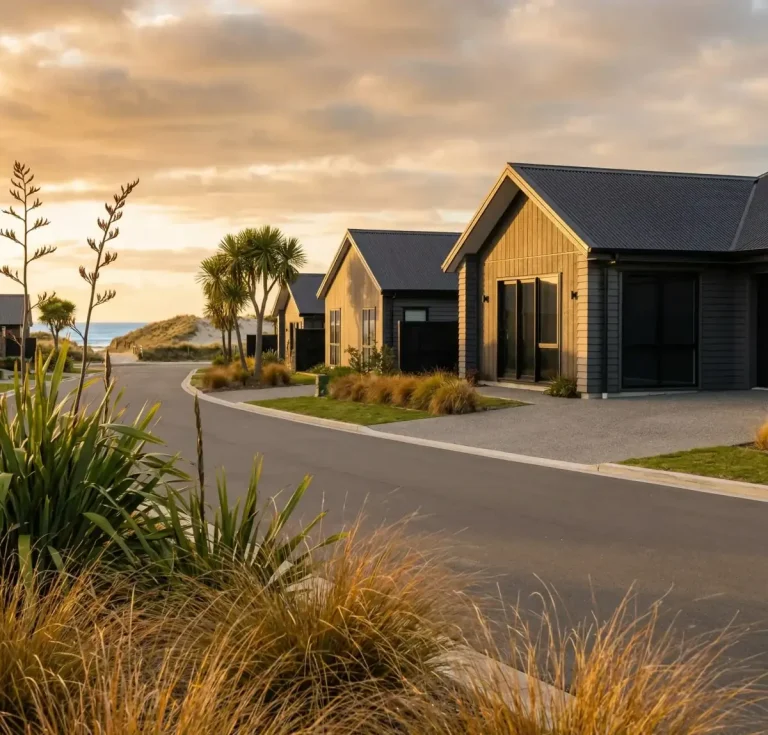
Papamoa combines its beachside setting with established residential streets and development in the wider Papamoa East and Wairakei area. A property near Papamoa Domain may involve a different set of questions from a house-and-land proposal further east. I focus on the actual agreement and property, rather than assuming the suburb gives you access to special lending rules.
You may be a first-home buyer deciding between those routes, a family changing homes or an owner reviewing an existing mortgage. I start with your available funds and income, then assess the property plan that those finances need to support.
For a build, I work backwards from the payment obligations. For an existing home, I focus on the offer conditions and settlement date.
I review the deposit, income, commitments and the reserve you want to keep, including housing costs during any build or move.
I check the proposed funding against the agreement. Your lawyer advises on the contract; I confirm the lender’s application and drawdown requirements.
I help gather the requested plans, specifications, contract, valuation or property information and explain conditions that are still outstanding.
Tell me about delays, variations or changes to income. I can ask the lender whether further assessment is needed before you rely on extra funds or a revised date.
The walkways through Papamoa’s stormwater reserves connect places such as Pacific View Road and Wairakei Reserve. Those reserves are part of the local setting, but neither proximity to a reserve nor a new-build label establishes the condition or risk of an individual section. I encourage an address-specific LIM review, current hazard checks and an insurance discussion.
For a new home, ask your lawyer to review the agreement, title or pending title, covenants and completion provisions. Get clarity on what the price includes: landscaping, driveways, fencing, window coverings and service connections may need separate allowances depending on the contract. I also discuss a contingency and any period of paying rent or an existing mortgage while the new home is unfinished.
Council monitors groundwater in the Mount Maunganui and Papamoa area. Any implications for foundations, drainage or a particular site need advice from the relevant professionals. I help with the lender’s evidence requirements; I do not certify land or building suitability.
My construction and new-build lending service explains how I help prepare a staged build or new-home purchase. If you are still assembling a deposit, start with first-home mortgage help so I can check what is realistic for your situation.
For an existing Papamoa mortgage, I can compare refinancing and refixing options with staying on your current arrangement. If you want to borrow for improvements, I consider affordability and the scope of the work as well as available equity.
This is an illustrative situation, not a client story. A first-home buyer agrees to buy a new home in Papamoa East and expects to settle while their finance pre-approval remains current. Construction then takes longer than expected.
I would check the approval’s expiry and remaining conditions, ask what updated information the lender needs and revise the buyer’s cash-flow plan for extra time renting. The lawyer would advise on the agreement and any change to settlement. I would not assume a previous approval, interest rate or valuation remains valid until the build finishes. Identifying those dependencies early is more useful than promising a quick approval at the end.
No. I check the lender’s current criteria, your finances and the particular property or build arrangement. Being in Papamoa East, Golden Sands or another development does not itself establish eligibility. Any low-deposit option needs an individual assessment.
The marketing label is not enough to tell. I look at the agreement and payment schedule: will you pay for land and construction in stages, or pay a deposit with the balance due on completion? Your lawyer should explain your obligations before you sign.
Contact me as soon as the timetable changes. I can check what the lender needs to renew or reassess the approval, which may include updated finances and property information. An extension or the same terms cannot be assumed.
Yes. A recent build does not replace due diligence on the address. Ask your lawyer about the LIM and relevant property records, obtain insurance terms and seek specialist advice if a site or building issue needs investigation.
Yes. I can look at the existing loan, proposed work and how you would repay additional borrowing. I check whether the lender needs quotes, consents, valuation or other evidence. Having equity does not automatically mean the extra lending will be approved.
I offer direct, one-to-one advice backed by more than 20 years in finance and lending. Read about my background or what clients say. For our first conversation, the purchase or build price, your deposit position and the expected dates will help me identify the next questions.
Still comparing locations? Use the Tauranga area guide. My Tauranga mortgage advice overview explains how I work across the wider area.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.