I’m Eddie Biesenbach, a Tauranga-based mortgage adviser helping buyers and homeowners in Te Puke. Whether you’re considering a house in town or a lifestyle property nearby, I help you check the borrowing against the home, the land and your own circumstances.
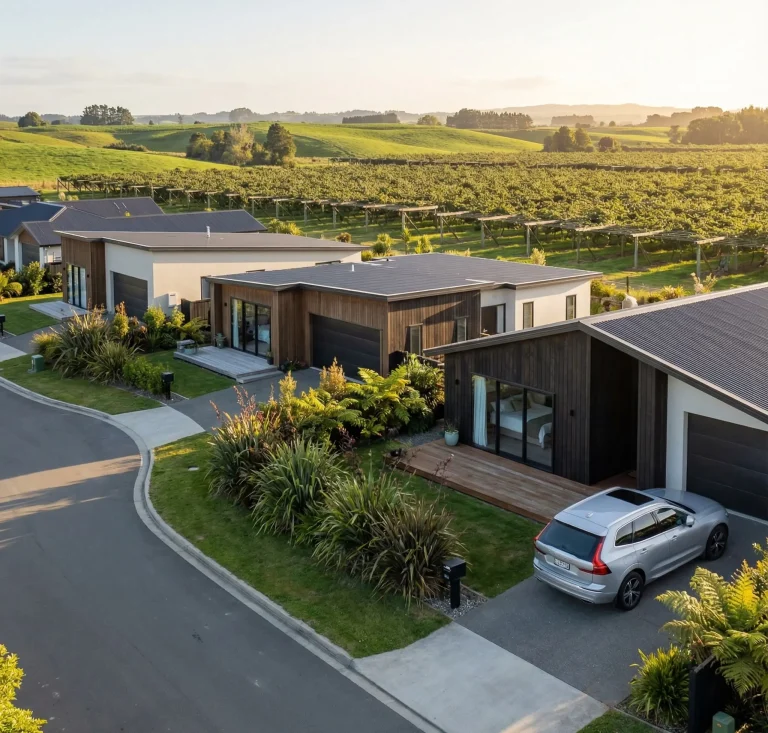
Te Puke is a Western Bay of Plenty town with its own centre along Jellicoe Street and a strong connection to the surrounding horticultural area. A home near the town’s shops and services is a different proposition from a house with land outside town. I want to understand which one you are buying before discussing the finance.
For a town property, I start with the purchase budget, title, condition and ongoing household costs. For a lifestyle property, I also ask about the size and use of the land, buildings beyond the house and how the property is serviced. The word “lifestyle” in a listing is a starting description; it does not establish how a lender will assess the property.
You might be buying a first home, moving from another area or reviewing a property you already own. I base the advice on your plans and financial information, rather than assuming how you earn your income because you are buying in Te Puke.
Nearby orchards alone do not tell me whether a home is acceptable security. I use the address, property documents and lender’s assessment. Your lawyer, accountant or rural specialist should advise on matters such as land-use permissions and any tax implications.
If your earnings vary seasonally, include overtime or come from self-employment, tell me early. I want to understand the full pattern, including quieter periods and existing commitments, before discussing a repayment level. The lender decides what income it can accept and what evidence it needs; one busy month is not a reliable basis for the whole plan.
That evidence may include payslips, an employment agreement and bank statements. For a business owner, financial statements and supporting information from your accountant may be needed. My self-employed home-loan service explains that preparation. A person buying in Te Puke may equally have a regular salary: I only investigate the income arrangements that apply to you.
If this is your first purchase, my first-home buyer service covers deposit preparation and the application. For a mortgage you already have, I can compare refixing or refinancing with your current arrangement, including costs and the remaining repayment term.
This is a hypothetical planning example, not a client story. A couple comparing a house in Te Puke with a home on land outside town prefer the second property. It has private wastewater, extra sheds and a small area used by someone else under an arrangement with the current owner.
I would ask for those details before relying on a residential pre-approval. Their lawyer would check the arrangement and title; relevant specialists would assess the services and condition. I would then clarify lender fit and the evidence required, while adding maintenance and insurance costs to the budget. The outcome could be proceeding, seeking different terms or deciding the property needs more investigation. There is no assumed approval.
You do not need a complete file to talk to me. The listing, your broad income and deposit position, and any offer deadline are enough to start identifying the next questions.
I ask what is included in the purchase, how you will use it and whether any land or buildings generate income. That helps me identify the appropriate lending discussion.
I review your deposit, income pattern, spending and debt, then allow for property costs and the cash reserve you want to retain.
I explain the lender’s document requirements and coordinate the finance information. Legal, building, rural-use and insurance questions stay with the relevant specialists.
I help you understand the outstanding finance requirements and proposed loan structure. Consult your lawyer before an unconditional commitment; a pre-approval may still depend on the property.
Yes. I help Te Puke buyers and homeowners directly and can arrange a suitable way to talk. Te Puke is a separate Western Bay of Plenty town; I do not have a separate office there.
It may be possible, but I need to check the land, its use, the buildings and the lender’s criteria. An operating orchard or other business activity can change the discussion. I will not assume a property qualifies from its marketing label or size alone.
Tell me how your income is earned and provide the available history. I can ask the lender what evidence it requires and how it will assess that income. Acceptance and the amount used depend on the individual application; seasonal work does not establish an automatic yes or no.
For an address in Western Bay of Plenty District, start with the council’s LIM and any relevant property-file records. Have your lawyer advise on the title and other checks. A LIM describes information held by council and does not replace a site inspection.
No deposit outcome follows from the location or age of the home alone. I check your finances, the exact purchase and current lender requirements. Allow for legal, inspection and moving costs alongside the deposit rather than committing every dollar to the price.
You deal directly with me, backed by more than 20 years in finance and lending. I began with Barclays International on the Isle of Man and later worked for three New Zealand banks. You can read about my background and client reviews before we talk. I’m based in Tauranga and can arrange a suitable way to discuss your Te Puke plans.
For other places I serve nearby, use the Tauranga and nearby areas guide. My Tauranga mortgage advice overview explains the wider service.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.