I’m Eddie Biesenbach. If you’re comparing an established Pyes Pa home with a property offering more land, I help you work out what each choice means for your mortgage and everyday budget. I start with the home you can buy and use today, and the borrowing you can comfortably manage.
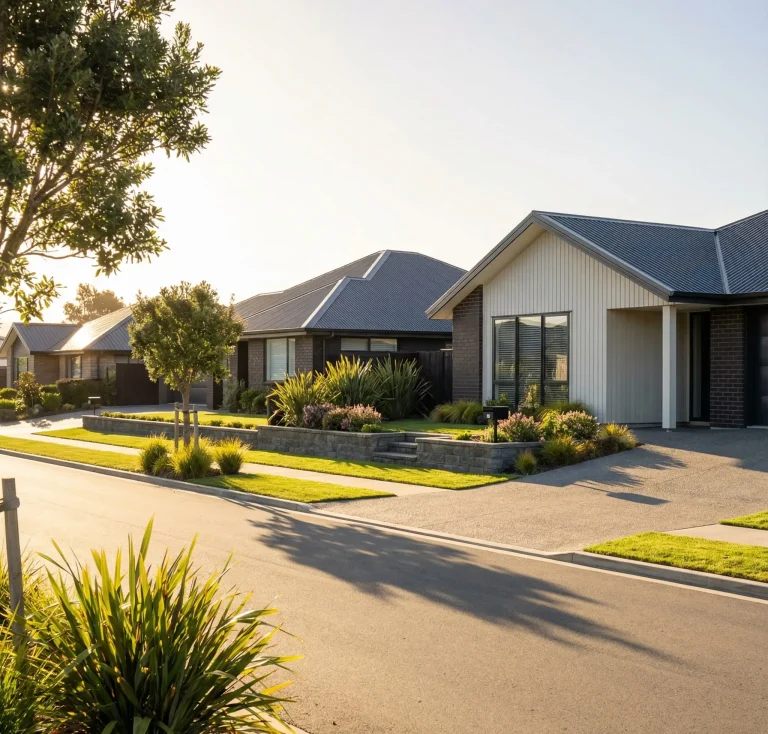
Pyes Pa includes established residential areas and a rural edge. I ask for the actual address early, whether you’re looking along the Pyes Pa Road corridor or towards Keenan Road. Land area, permitted use and the work a property needs are more useful to a lending discussion than the suburb name alone.
The Lakes, within the Pyes Pa West growth area, has its own subdivision setting. If that is where you are buying, my The Lakes mortgage guide focuses on the title, house and future alterations there. This page focuses on the wider Pyes Pa established-home and lifestyle-property choice.
An established home. I want to understand the purchase price plus any work you expect to do soon after moving. A building inspection and the relevant council records can help your advisers identify maintenance or past alterations to investigate. I can then discuss the borrowing with clearer costs rather than an optimistic renovation allowance.
A larger or lifestyle property. Tell me about the house, land, outbuildings and intended use. If keeping animals, running a business or adding another building is part of the plan, ask your lawyer and council what is permitted. I would not include hoped-for income or subdivision proceeds as though they were already available.
Land marketed for future growth. As at October 2026, council is still investigating the feasibility and staging of the proposed Keenan Road urban growth area. This is separate from buying an existing Pyes Pa home. Before relying on development potential, get the actual zoning, title restrictions and servicing position checked. I base our initial finance discussion on the verified property and your present repayment position.
For an initial purchase, my first-home buyer service helps you prepare the deposit and financial information. If buying a home and improving it is your plan, I can discuss renovation and construction finance once the scope and costs are clearer.
If you already own in Pyes Pa, I can review refinancing or refixing options against your existing loan, future plans and switching costs. A different rate alone does not establish whether moving lenders is worthwhile.
Imagine a couple comparing a Pyes Pa family home with a larger property that has an older shed. They intend to live there, use the shed for a hobby and repair it over time. Their purchase budget uses nearly all their savings.
I would separate the price from the repair budget and ask what cash they want left after settlement. Their lawyer would check the permitted use and title; an appropriate building professional would advise on the shed. With those findings, I would revisit the loan amount and repayments before an application proceeds. This is a hypothetical planning example, not a client result or approval promise.
I help organise the finance evidence and explain the outstanding questions. Your lawyer and property specialists advise on the legal and physical condition of the home.
I review income, deposit or equity, existing debts and regular expenses. Tell me about planned changes such as reduced working hours, and the repayments you would be comfortable carrying.
Send the listing, address and any reports already available. I ask about land, outbuildings and proposed work, then clarify the information a suitable lender would need to consider the property.
I help you bring identified rates, insurance, maintenance and improvement costs into the budget. For a larger property, I also ask what practical upkeep you expect to pay for.
I prepare the lending proposal, discuss suitable options and explain any conditions. I work with you, the lender and your lawyer on the mortgage requirements before settlement.
I would check the actual home and transaction. An established house, a newly completed property and a land-and-build project are different proposals. I confirm the relevant lender criteria for your circumstances rather than infer a deposit requirement from the address.
Yes. I start with how you intend to use it and the available property information, then assess suitable finance options. Your lawyer should review the title and permitted uses. I cannot confirm a lending outcome from the acreage or the word lifestyle alone.
I would not rely on an unconfirmed future subdivision to make today’s repayments affordable. Have the planning, legal and servicing questions assessed separately. I can discuss the financing implications of a properly documented proposal, without treating a growth-area label as consent to develop.
I can assess that with you. I need a realistic scope and cost, your available funds and the proposed repayments. The lender may require further documents depending on the work. Discuss the full plan before committing to either the property or a building contract.
Yes. I can compare the borrowing and ownership costs for the specific homes on your shortlist. That keeps the decision grounded in the properties, your budget and your plans, without assuming that one neighbourhood has easier lending.
I’m based in Tauranga and bring more than 20 years of lending experience overall, including Barclays International in the Isle of Man and three New Zealand banks. You deal directly with me. Read about my background or what clients have shared, then send me the property and the questions you want to resolve.
For the wider area, explore my Tauranga suburb guide. For an overview of my advice and approach, visit mortgage advice across Tauranga.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.