I’m Eddie Biesenbach. In Tauriko, I start by understanding exactly what you are buying and how you will use it. A home, a rural-residential property and premises used for business raise different questions. I help turn the details into a clear mortgage proposal, with realistic costs and repayment expectations.
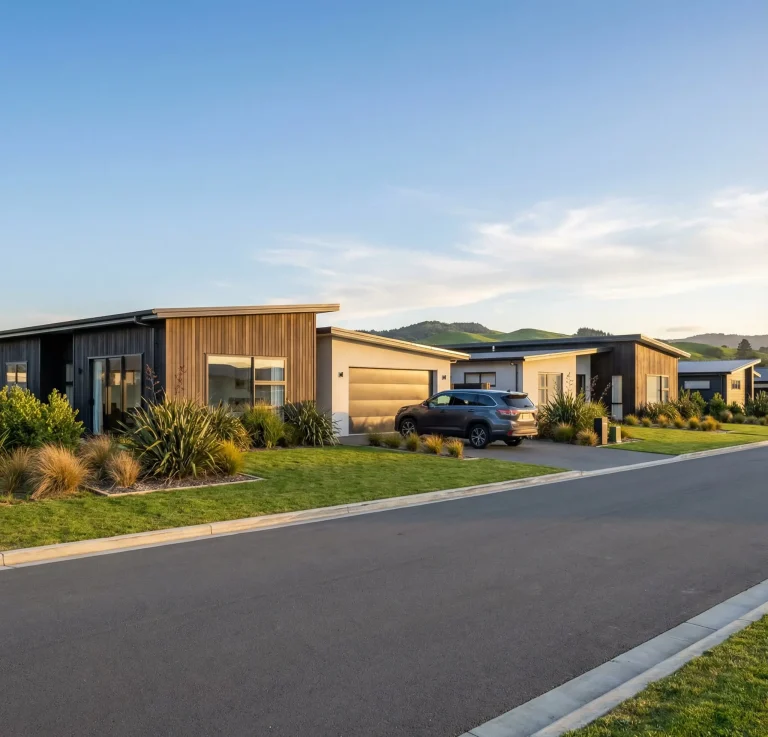
Tauriko’s property setting includes the Business Estate, rural-residential land around lower Belk Road and the separate Tauriko West housing development beside the Wairoa River. These are different places and uses. Council’s planning records distinguish Belk Road rural-residential land from the industrial extension, so I would not describe every property near the Business Estate as commercial or mixed-use.
The established subdivision at The Lakes is another distinct setting. If a listing uses Tauriko loosely, send me the address and legal description. I want the finance discussion to follow the actual property rather than the marketing label.
The use you need. Will you live in the house, store equipment, work from an outbuilding or use part of the land to earn income? Tell me the full plan. Your lawyer and council can establish zoning, title restrictions and necessary permissions. I can then clarify how a lender would assess the documented proposal.
The costs you can substantiate. I separate household income and spending from business cash flow. If earnings come through your own business, I help organise the available financial statements and other relevant evidence. An attractive workshop or a large shed is useful only if its intended use, cost and funding fit the plan.
The stage of a new property. Tauriko West is a staged housing development, with infrastructure requirements linked to development stages. When considering a section or future home, I ask what the particular contract includes, when title and settlement are expected, and what evidence exists for access and service connections. I do not treat a wider project announcement as confirmation that an individual lot is ready.
If you run your own business, my self-employed mortgage service focuses on presenting your income and commitments clearly. Working near the Business Estate does not by itself change your personal home-loan needs; I look at how you are paid and what you are purchasing.
For a section, new house or substantial alteration, I can help with construction and renovation finance. Bring the actual scope and agreement so I can discuss payment timing and funding. If your main purpose is business or development rather than a home, tell me at the start so I can clarify the appropriate finance discussion.
Imagine a self-employed buyer looking at a Tauriko rural-residential property with a separate shed. They want to live in the house and use the shed for their existing business. The listing describes it as ideal for working from home, but the buyer has not checked the permitted activity or insurance.
I would ask for the business financial evidence and a clear description of the intended use. Their lawyer, council adviser and insurer would resolve the property-use questions. I would use the confirmed information to assess lending options, without assuming a standard home loan covers every use. This is a hypothetical example, not a completed client transaction or a guarantee of finance.
I focus on the facts a lending decision needs. If something is still a proposal, I keep it identified as a proposal throughout the discussion.
Send me the address, listing and your intended use of the home, land and any extra buildings. Include the price, deposit, timing and work you expect to fund.
I review the household position and, where relevant, the business information supporting your income. I ask about ongoing commitments and any changes the move would make to your costs.
I identify information needed for finance, while your lawyer, insurer and property professionals advise in their own areas. If the intended use changes after their review, I reassess the lending proposal with you.
I explain the available options, proposed structure and outstanding requirements. You can then consider the repayments and risks with a clear understanding of what the lender has and has not agreed to.
I would not decide that from its location. The title, zoning, actual use and lender’s assessment need to be considered. Send me the property details and your plans so I can establish the right questions before an application is submitted.
Check that with your lawyer, council and insurer before relying on it. I need the intended use disclosed accurately in the finance discussion. A listing’s description or the presence of an existing shed does not confirm the permissions or lending treatment.
No. I would ask for the specific title, consent, servicing and contract information. Council describes staged infrastructure and development. Your lawyer and technical advisers should establish what is available for the particular lot and what still needs to happen.
Yes. I help organise the income evidence and explain the business context alongside your household commitments. What a lender needs depends on the application. I will discuss any gaps in the evidence rather than promise that self-employment qualifies for a particular product.
I would not base your loan on a predicted rise in value or future rental demand. I work with your current financial position and the valuation information the lender accepts. A development announcement is useful context, not an agreed valuation or approval.
You deal directly with me. I’m based in Tauranga, with more than 20 years of lending experience overall, including Barclays International in the Isle of Man and three New Zealand banks. Read about Eddie and my approach to mortgage advice, then we can work through what your Tauriko purchase needs.
For other localities, use the Tauranga suburb guide. My Tauranga mortgage advice overview explains the wider service.
Led by Eddie Biesenbach, Best Mortgages brings 20+ years of experience directly to your door. We help Tauranga & Bay of Plenty locals—from First Home Buyers to Self-Employed Investors—work through their home loan options without the bank queues
Head Office: 12 Bay Street, Matua, Tauranga 3110
Ewald (Eddie) Biesenbach (FSP 320426) provides financial advice through The Best Limited trading as Best Mortgages (FSP 724451, NZBN 9429043352067). The Best Limited holds a Financial Advice Provider licence issued by the Financial Markets Authority.